How Insurance Determines Total Loss in Georgia
When you ask how insurance determines total loss, the short answer is that the insurer compares the expected cost and consequences of repairing your car with the vehicle’s pre-crash value. The decision is not based only on the repair estimate. The insurer may also review safety, parts, labor, salvage, comparable vehicles, your policy, and Georgia claim rules.
Request a free case evaluation with Gastley Law or call (770) 557-2838 today.
Insurance generally declares a vehicle a total loss when repairing it is not economically or practically reasonable compared with its actual cash value. Adjusters review the repair estimate, pre-loss vehicle value, salvage, comparable vehicles, title issues, and policy terms. A total-loss decision and the amount of the settlement are separate questions.
For Georgia drivers, that distinction matters. An insurer can decide that a car should not be repaired and still produce a valuation that does not accurately reflect the car’s condition or local market. This guide explains each part of the decision and the evidence you can use to challenge an inaccurate total-loss offer.
What does it mean when insurance declares a car a total loss?
A total loss means the insurer will resolve the property-damage claim based primarily on the vehicle’s value rather than paying to restore the vehicle through ordinary repairs. The car may be badly damaged, unsafe to repair, too expensive to repair, or worth less than the projected cost of returning it to its pre-crash condition.
The decision is not the same as saying the vehicle has no value. A totaled car may have salvage value, usable parts, or a possible repair path. It means the insurer’s selected claim method treats a cash settlement, replacement, or another resolution as more appropriate than paying the full repair bill.
It is also important to separate two questions:
- Is the car a total loss? This concerns whether repair is economically or practically reasonable.
- How much is the claim worth? This concerns the vehicle’s actual cash value, deductions, taxes, fees, deductible, and any applicable policy terms.
Those questions often become confused during a claim. Even if the total-loss decision is reasonable, the valuation can still contain an incorrect trim level, missing equipment, inaccurate mileage, unsupported condition deduction, or unsuitable comparable vehicle.
How do insurance companies decide a vehicle is a total loss?
Insurance companies usually begin by estimating the cost to repair the damage and comparing that figure with the car’s actual cash value before the accident. They may also consider hidden damage, supplemental repair estimates, whether the vehicle can be repaired safely, the availability of parts, projected delays, and what the vehicle could bring as salvage.
| Factor | What the insurer reviews | Why it matters |
|---|---|---|
| Repair estimate | Parts, labor, paint, diagnostics, towing, storage, and likely supplements | The first repair estimate may not show all damage |
| Actual cash value | Age, mileage, condition, trim, options, history, and market comparables | It sets the reference point for repair economics and the settlement |
| Safety and feasibility | Structural damage, vehicle systems, parts availability, and repair quality | A repair that looks affordable may not be practical or safe |
| Salvage value | Expected value of the damaged vehicle, parts, or scrap | It can affect the insurer’s net loss and an owner-retained settlement |
| Policy and state rules | Coverage, deductible, appraisal provisions, and applicable regulations | The claim method and payment terms depend on governing documents |
There is no universal percentage that answers every total-loss question. Thresholds and methods can differ by state, policy, claim type, insurer, and vehicle facts. A percentage reported online may be a useful starting point for research, but it should not replace the policy, the complete valuation report, or current Georgia guidance.
In Georgia, the rules governing certain first-party total-loss settlements address how an insurer may pay a cash equivalent or replace the vehicle. The Georgia total-loss vehicle regulation describes comparable vehicles, local-market evidence, and taxes and transfer fees in the cash-equivalent method. The rule is not a promise that every claim will use one identical formula, so read the policy and claim documents closely.
How does the repair cost compare with actual cash value?
The repair-versus-total-loss comparison starts with two estimates: what it should cost to repair the car and what the car was worth immediately before the crash. If the projected repair cost approaches or exceeds the relevant value, the insurer may determine that repairing the car is not economically reasonable. The comparison can change as hidden damage is discovered.
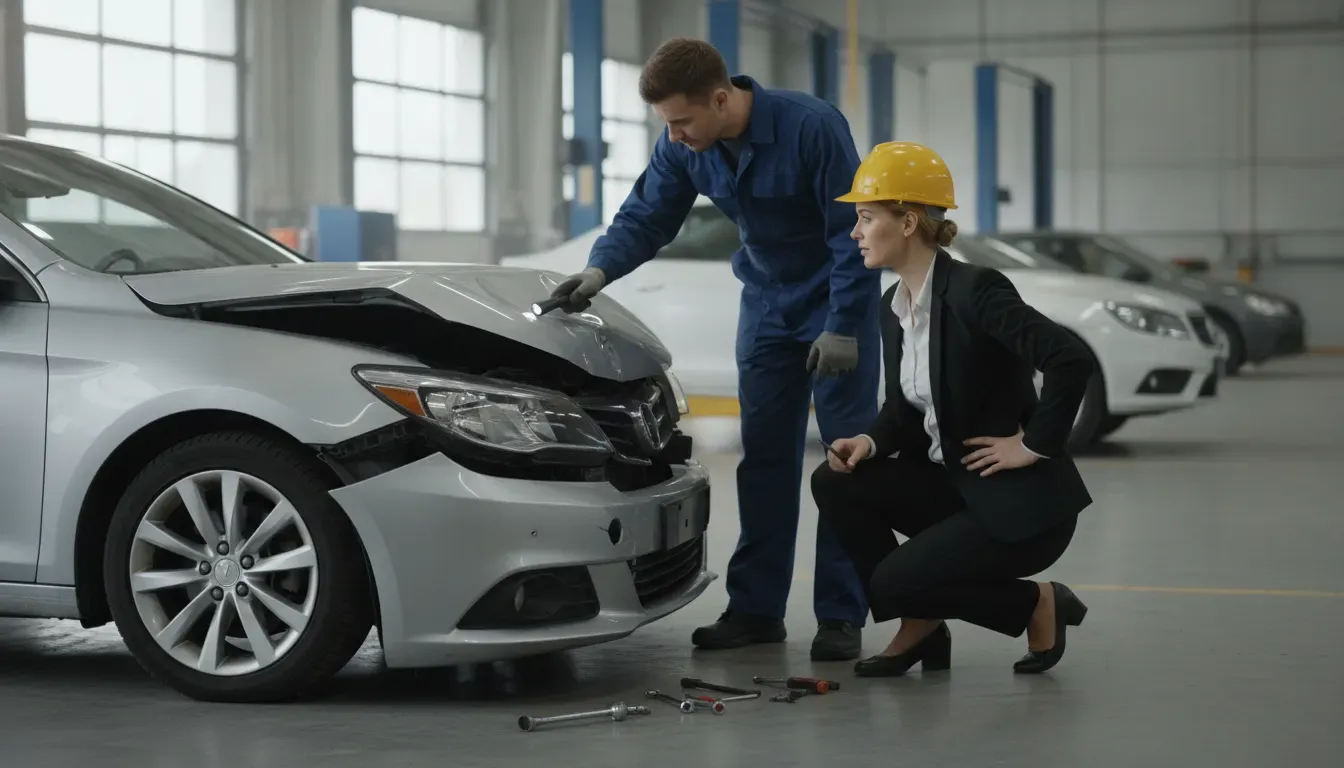
For example, a visible bumper, hood, and headlight estimate may not include damage behind the bumper, suspension problems, sensors, frame measurements, or calibration. A body shop may issue a supplemental estimate after teardown. Towing, storage, rental exposure, and parts delays can also affect the practical repair decision, although the precise treatment varies by claim and policy.
What is actual cash value?
Actual cash value, often called ACV, is generally the vehicle’s market value immediately before the loss, adjusted for relevant depreciation and condition. It is not automatically the amount you originally paid, the remaining loan balance, or the price of a new vehicle. A credible ACV analysis should identify the vehicle accurately and explain the evidence behind the number.
Check whether the report correctly identifies:
- Year, make, model, trim, drivetrain, and body style.
- Mileage and the vehicle’s pre-accident condition.
- Factory options, technology packages, premium equipment, and documented upgrades.
- Prior damage, maintenance history, tires, and other condition details.
- Comparable vehicles, their locations, listing dates, mileage, equipment, and condition.
One wrong field can distort the comparison. A base trim used for a higher trim, a front-wheel-drive comparison used for an all-wheel-drive vehicle, or a materially different mileage range may justify a closer review. Keep the correction specific and support it with records rather than relying only on a general statement that the offer is too low.
How is the vehicle’s salvage value used?
Salvage value is the estimated amount an insurer could recover from the damaged vehicle through parts, salvage sale, auction, or another channel. It can affect the insurer’s net economics and may be used as a deduction if the owner keeps the totaled car. Salvage value is not the same as the car’s pre-crash actual cash value.
If you are offered an owner-retained option, ask for the salvage deduction and the assumptions behind it in writing. Compare that deduction with the vehicle’s actual condition, the cost of towing and storage, repairs, inspection, title work, registration, insurance, and the risk that repairs will reveal additional damage.
Keeping the vehicle can create title and registration consequences. The Georgia Department of Revenue salvage-title guidance explains that salvage vehicles cannot be operated legally on public roads in Georgia until the applicable process is completed. Confirm current requirements with the state and your insurer before deciding to retain the vehicle.
A salvage deduction should also be separated from the question of whether the original ACV was accurate. If the insurer used the wrong vehicle value, the owner-retained settlement may be wrong even if the salvage calculation itself is reasonable. Ask for both figures and review how they connect.
What should Georgia drivers check in a total-loss valuation?
Georgia drivers should treat the valuation report as a set of checkable assumptions, not as an unchangeable answer. Start with the vehicle description, then inspect the comparables, adjustments, condition rating, and included taxes or fees. Preserve evidence before online listings disappear or a claim representative changes the file.
- Request the complete report. Obtain the comparable list, vehicle descriptions, adjustments, condition information, and source data used to reach the offer.
- Verify the subject vehicle. Check the trim, drivetrain, mileage, options, prior condition, and reported history against your records.
- Test every comparable. Record the listing date, location, mileage, equipment, condition, and whether the price is an asking price or a completed sale.
- Document omitted value. Gather the window sticker, purchase records, service invoices, photographs, tire records, option records, and proof of upgrades.
- Check the geography. A distant vehicle or a vehicle from a materially different market may not represent what it would cost to replace your car in the relevant area.
- Review deductions and fees. Confirm the deductible, salvage deduction if applicable, taxes, license fees, transfer fees, towing, and storage treatment.
- Write a focused response. Identify each incorrect assumption, attach the supporting evidence, and request a revised valuation or a clear explanation.
Gastley Law’s total loss appraisal resource provides related guidance on reviewing vehicle value. Its focus is valuation evidence, while this article explains the broader repair-versus-total-loss decision.
Want help reviewing a total-loss valuation or settlement? Contact Gastley Law for a free case evaluation or call (770) 557-2838.
Can you negotiate a total-loss decision or settlement in Georgia?
You can ask an insurer to reconsider a total-loss decision or settlement when the repair estimate, vehicle value, salvage deduction, or claim method rests on inaccurate information. Negotiation is strongest when it identifies a concrete error and supplies evidence that addresses that error. A disagreement with the number alone may not show why it should change.
For first-party claims, review the policy’s appraisal provision and any notice requirements. Georgia’s regulation may be relevant to certain first-party vehicle settlements, but the policy and claim facts control the available process. For third-party claims, liability, available coverage, and the other driver’s insurer can change the practical path. Do not assume that a first-party procedure applies identically to a claim against another driver’s carrier.
Before signing a release or accepting a settlement described as full and final, review what claims and losses it covers. A total-loss payment may not resolve every issue involving a loan, rental expenses, loss of use, personal property, title, or other property damage. The language of the release matters.
Gastley Law focuses on diminished value and property damage claims for Georgia vehicle owners. Its related guide to insurance for a totaled car addresses additional payout considerations. If your car is repaired rather than totaled, diminished value may be a separate issue from the pre-crash valuation used in a total-loss claim.
Frequently Asked Questions
What percentage of a car’s value makes it a total loss?
There is no single percentage that answers every claim. The applicable state rules, policy, claim type, repair estimate, actual cash value, safety concerns, salvage, and insurer method all matter. Ask for the calculation and the full valuation report instead of relying on a general percentage from another state.
How do insurers calculate the value of a totaled car?
Insurers generally estimate actual cash value using the vehicle’s age, mileage, condition, trim, equipment, history, and comparable vehicles in the relevant market. Review the report for incorrect vehicle details, missing options, unsuitable comparables, unexplained adjustments, and deductions that are not supported by the claim file.
Can I keep my car after insurance declares it a total loss?
Sometimes an insurer may offer an owner-retained option, but the settlement can be reduced by salvage value and the vehicle may face title, registration, inspection, repair, insurance, and resale consequences. Confirm the current Georgia requirements and request the salvage calculation before choosing to keep the vehicle.
Does salvage value reduce a total-loss settlement?
It can, particularly when the owner keeps the damaged vehicle. Ask for the salvage deduction in writing and separate it from the vehicle’s pre-crash actual cash value. A reasonable salvage deduction does not correct an inaccurate ACV, so both parts of the settlement should be reviewed.
What should I do if the insurance total-loss offer is too low?
Request the complete valuation report, verify the vehicle details, collect dated local comparables and condition evidence, identify each error, and send a focused correction request. Review the policy for appraisal provisions and deadlines. Consider legal guidance before signing a release if the valuation gap is significant or the file is disputed.
Is a total-loss valuation the same as diminished value?
No. A total-loss valuation addresses what the vehicle was worth immediately before the crash when the insurer is resolving a total-loss claim. Diminished value is the market-value loss that may remain after a vehicle is repaired. They are different concepts and may require different evidence and claim analysis.
Request a free case evaluation with Gastley Law or call (770) 557-2838 today.